If you're listing a house in Millington this year, there's a good chance your buyer's paycheck comes from the Navy. Naval Support Activity Mid-South sits right here in town, and VA-financed offers can raise questions about closing timelines and possible repair requests. Some concerns relate to rules that have changed. The paperwork that can slow a VA closing in Millington includes a Tennessee-specific inspection requirement that applies to every VA purchase loan here, regardless of the buyer, according to the VA's state requirements list.
NSA Mid-South is the Navy's Human Resources Center of Excellence, home to Navy Personnel Command and several other major commands, supporting roughly 7,000 enlisted, officer, civilian, and contractor personnel. It's a shore-duty installation, which means the people stationed here tend to keep a steady schedule and stay in one place longer than someone on a fleet-heavy assignment. On-base family housing only runs about 280 units, managed by Hunt Military Communities, so most incoming families end up renting or buying somewhere in the surrounding community. A good share of that house hunting turns into VA offers on Millington homes.
2026 Basic Allowance for Housing rates for the Memphis military housing area, which covers Millington, range from $1,530 a month for an E-1 through E-4 without dependents up to $2,679 for an O-7 with dependents.
| Pay grade | 2026 monthly BAH, Memphis TN MHA |
|---|---|
| E-1 to E-4, no dependents | $1,530 |
| O-7, with dependents | $2,679 |
Even at the lower end of that range, a household using a zero-down VA loan is often working with a monthly housing budget that lines up comfortably with what's actually for sale here. In August 2026, Millington homes carried a median list price around $300,000 and spent a median of 82 days on the market. That's not a market where VA buyers are stretching to compete. It's one where they're often a very natural fit.
Why the VA Offer Got a Reputation It Doesn't Fully Deserve
Some of the caution around VA offers is inherited folklore. According to Chase, until 2022, VA borrowers were barred from paying for their own termite inspection, which meant the seller almost always covered that cost by default. That rule changed under VA Circular 26-22-11, and veterans can now pay for the inspection themselves if they choose, though it's still a negotiable item like any other closing cost. The rest of the caution tends to come from confusing a VA appraisal with a full home inspection. They're not the same thing, and the appraisal is narrower and more predictable than most sellers assume.
What a VA Appraisal Actually Checks
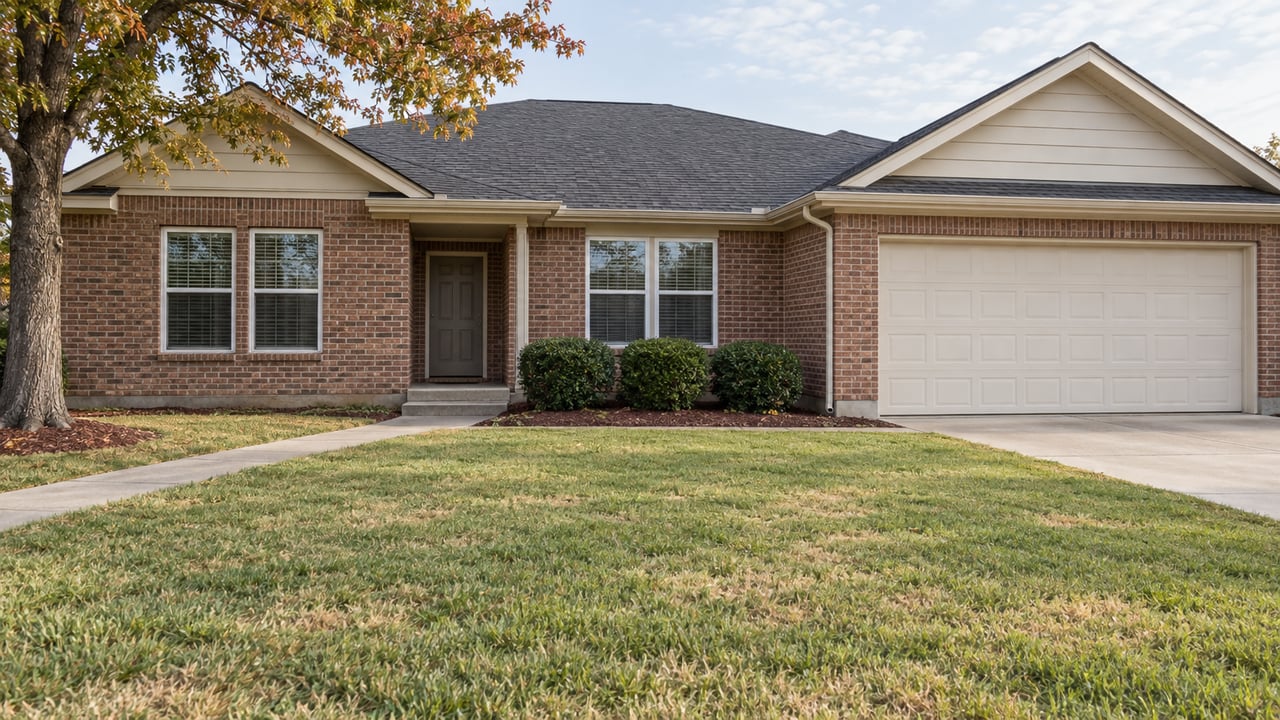
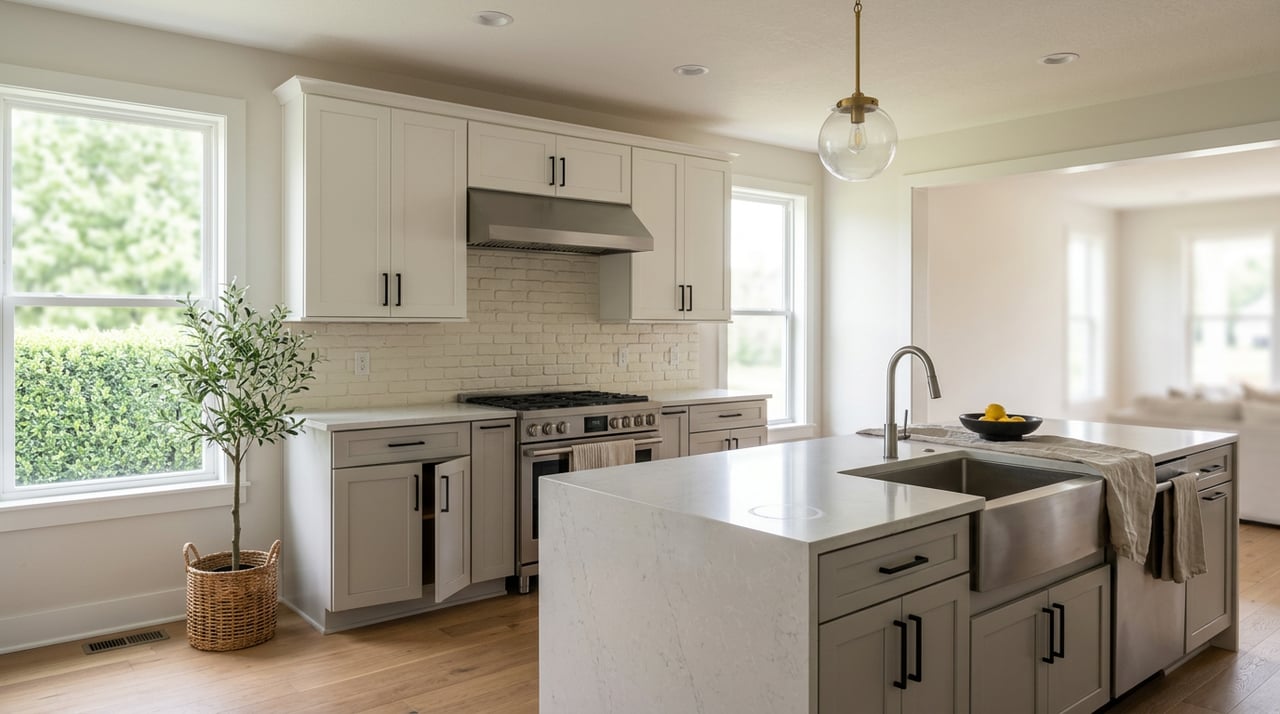
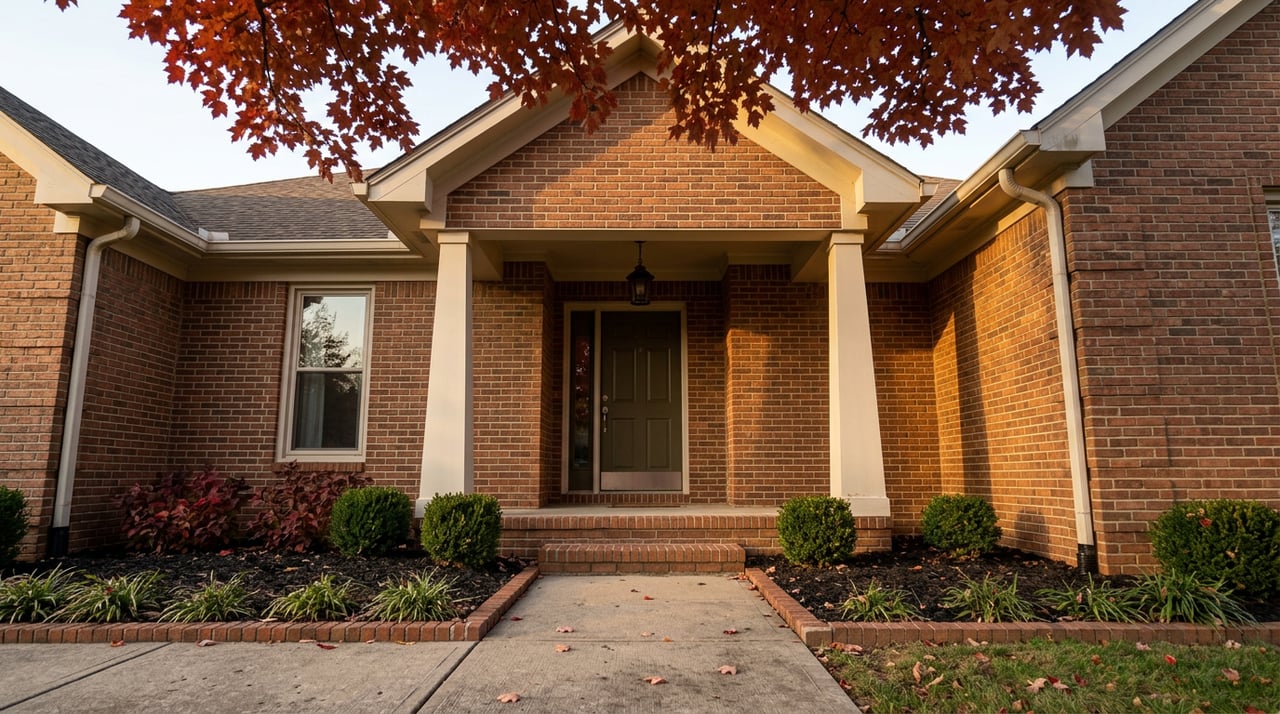
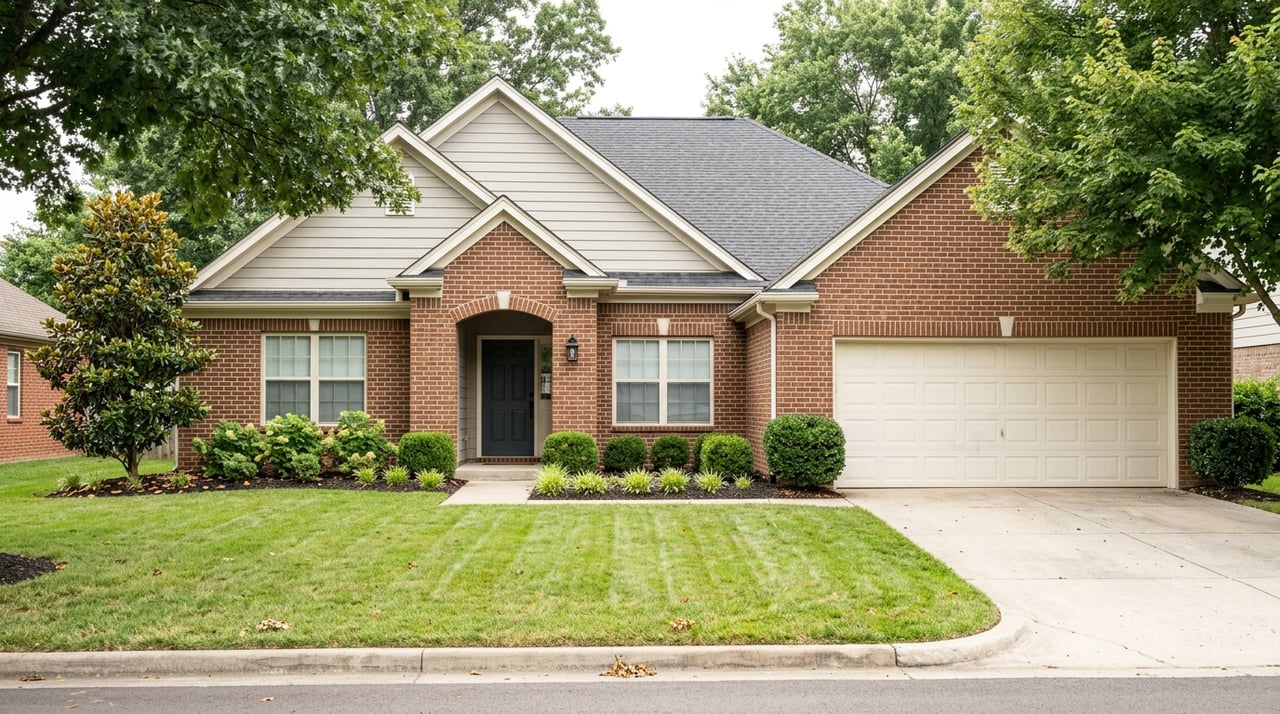
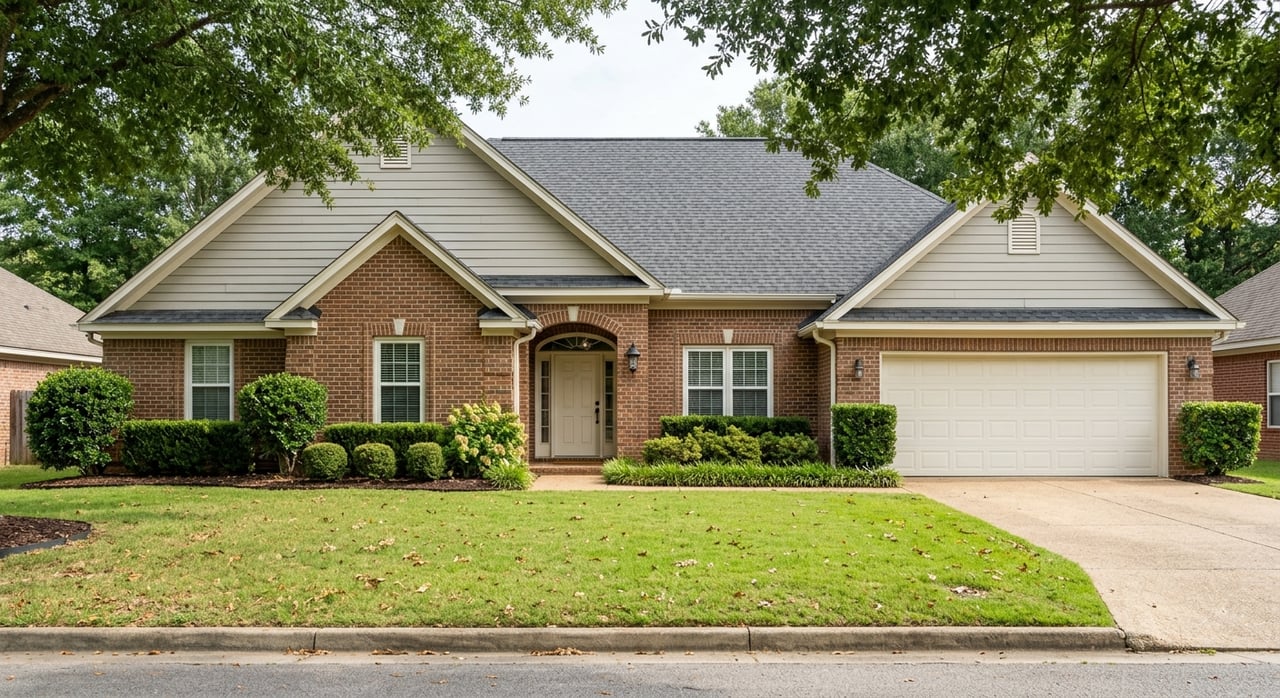
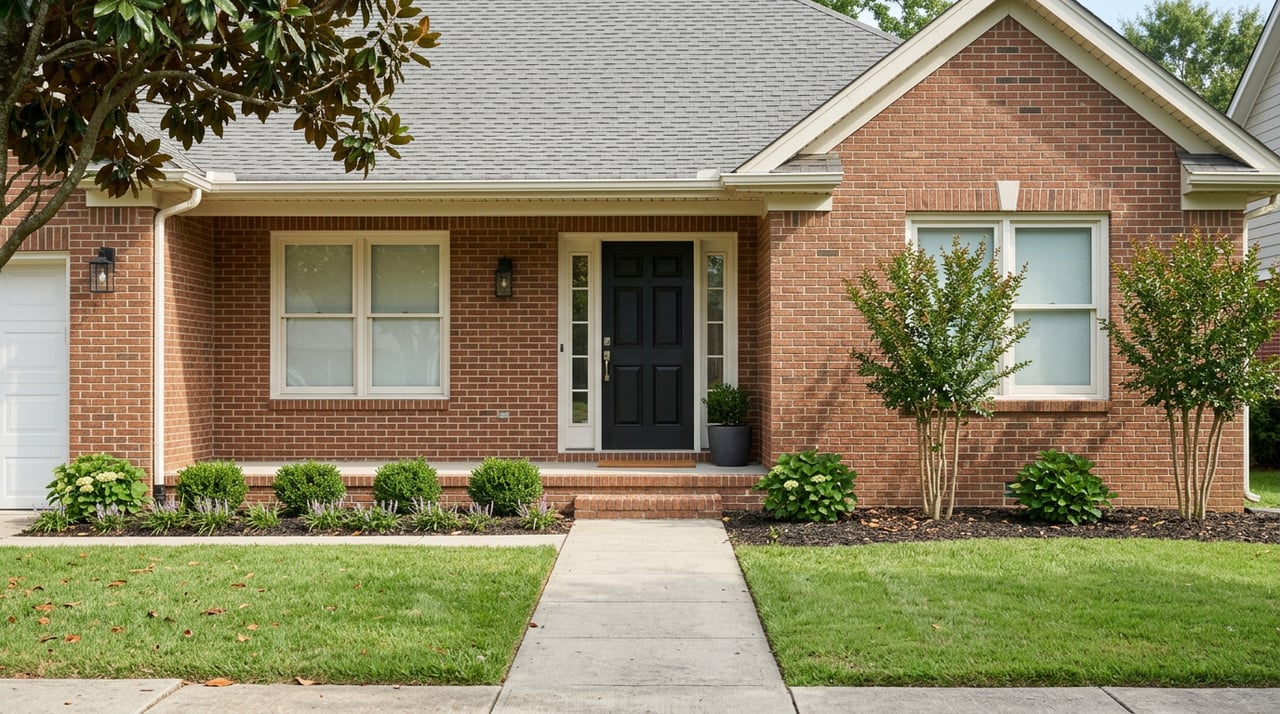
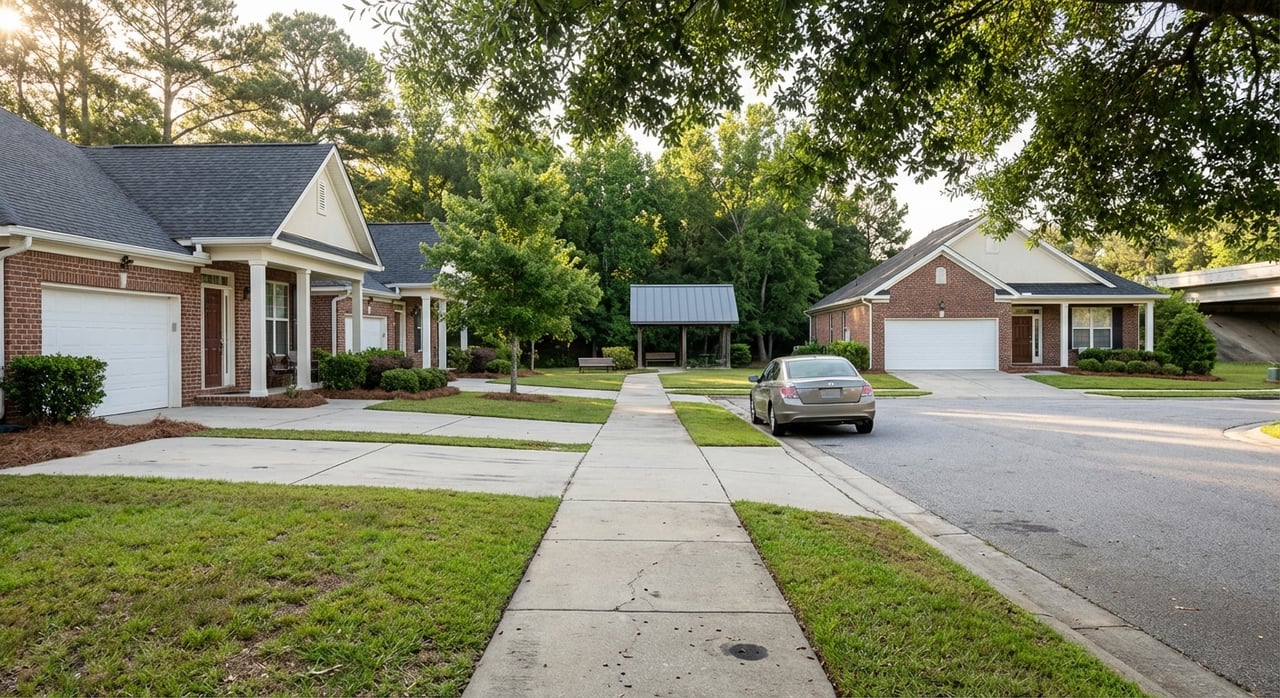
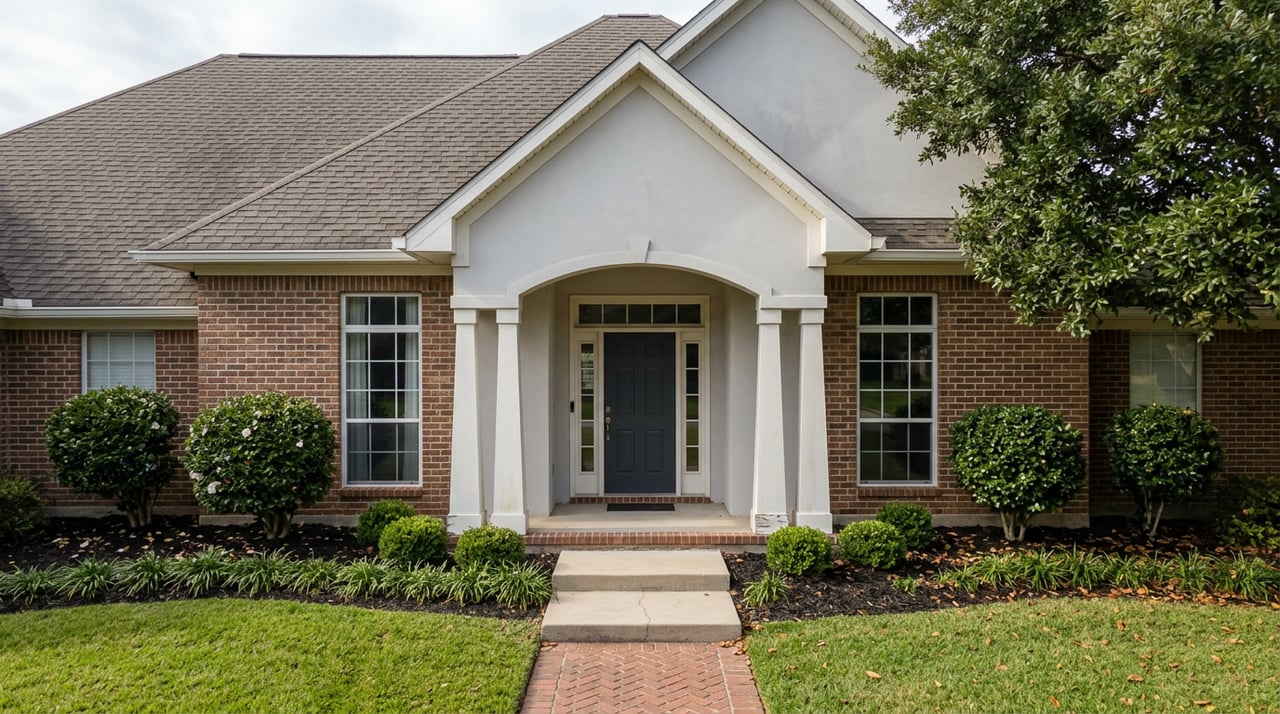
A VA appraisal does two jobs. It confirms the home's market value, and it confirms the property clears the VA's Minimum Property Requirements, a baseline safety and soundness standard, not a line-by-line inspection. According to VA Loan Network, lead-based paint only becomes an issue on homes built before 1978. Most well-kept Millington homes, including the classic brick single-story houses common around town, clear these requirements without much drama.
The One Step That Actually Slows Things Down
Tennessee is one of the states where the VA requires a wood-destroying insect inspection on every purchase loan, not just when an appraiser happens to spot a problem. That's confirmed directly on the VA's own list of state requirements. The inspection uses a standard form called an NPMA-33, stays valid for 90 days according to the VA Loan Network. It applies to every VA buyer in Millington no matter how the home shows, because it's a statewide rule, not a judgment about the property or the person buying it. Sellers who know this ahead of time can have the inspection done, or at least budget for it, before they ever get an offer, which removes one contingency that would otherwise surface after a contract is already signed.
If the Appraisal Comes in Under Contract Price
According to The Federal Savings Bank, when a VA appraisal comes back below the agreed sale price, the agent or lender has roughly two days from the Notice of Value to invoke a process called Tidewater, submitting additional comparable sales to support the original number before the value becomes final. This exists to protect against an appraiser working with incomplete information, not to force a price cut. Once the Notice of Value is issued, it stays valid for six months, which gives both sides room if the deal needs a little more time to work through repairs or paperwork. It's also worth knowing that the VA assigns the appraiser directly through its own system rather than letting the lender choose one, a deliberate independence measure meant to keep the valuation free of outside pressure. A low appraisal may prompt questions about the value and the comparable sales used. That process can help clarify whether the agreed price is supported by the market.
Timing a Listing Around Who's Actually Buying
Permanent change of station moves at installations across the country cluster between March and August, timed around the school calendar. That stretch has already passed for this year, but the pattern repeats every summer, which means a spring listing typically draws a heavier mix of PCS-driven VA offers than a fall or winter one does. That doesn't make a fall listing a bad idea. It just means the buyer pool right now leans a bit more toward local moves and less toward incoming transfers, which is useful context when you're setting expectations for how quickly an offer might come in and what kind of financing it's likely to carry.
What This Means When You List
None of this is a reason to treat a VA offer with suspicion. It's a reason to prepare for the specific, knowable steps that come with it. Getting a termite inspection done ahead of your first showing, understanding which repair items are actually MPR concerns versus cosmetic wear, and knowing how Tidewater protects both sides if an appraisal comes in low all add up to a smoother listing period, whether your eventual buyer finances conventionally or through the VA. This is the exact kind of groundwork Teresa Ervin brings to a listing, drawing on her ABR, AHWD, and MRP credentials, the last of which is specifically built around understanding how military relocation timelines and financing actually work on the ground in a town like Millington.
A Few Quick Questions
Do I have to pay for the termite inspection as the seller? Not automatically. Since the 2022 rule change, veterans can cover that cost themselves if they choose. It's still a negotiable line item, and many sellers agree to cover it as part of the offer, but it's no longer a default expectation.
Does a VA-financed offer close slower than a conventional one? Not inherently. The appraisal timeline follows standard VA guidelines and typically runs comparable to other loan types. Most delays come from repair items flagged during the MPR review, the same kinds of issues that could show up under any lender's appraisal.
What if my home was built before 1978? Lead-based paint only becomes an issue on homes built before 1978.
If you're thinking about listing in Millington and want to talk through what your specific home and street might look like to a VA buyer, or any buyer, Teresa Ervin Realty is happy to walk through it over a cup of coffee. Let's Get A Coffee and figure out your timeline together.
This article is general information, not legal, tax or financial advice. Consult a qualified professional about your situation.